Bill Simmons, the popular sports podcaster who has championed sports betting, is under review by the Massachusetts Gaming Commission after he admitted on a recent episode to using his daughter’s boyfriend to place bets for him.
The commission announced the review Tuesday, two days after Simmons said on an episode of his podcast that he’d used a proxy on multiple occasions to log in to his account and make wagers in Massachusetts.
Simmons, founder of The Ringer, is based in California, where sports betting is not legal. In Massachusetts, mobile and online betting is allowed.
But proxy betting — having someone place bets on behalf of someone else — is illegal in Massachusetts and is not allowed by FanDuel, the sportsbook with which the wagers were issued.
Marcin Golba / NurPhoto via Getty Images file
“The Commission is aware of the comments made on the Bill Simmons Podcast and staff are currently reviewing the matter,” an MGC spokesman said in a statement.
FanDuel is the exclusive sports betting partner of The Ringer. A spokesperson for the sportsbook told NBC News it reported the matter to the MGC and voided Simmons’ bets.
On the podcast episode, Simmons said there were bets “that I really wanted to get in — the UCLA overs. But Houston, the market had not shifted appropriately yet. I can’t have my daughter do it; my dad would have no idea how to do it.”
But, Simmons said, he trusted his daughter’s boyfriend and allowed him to log in to his FanDuel account.
“I get the code to make sure it’s me to my phone, I give him the code, he logs in. And I have all this money that I had from last year because I actually hit a bunch of futures last year. And he’s putting in bets for me,” Simmons said, adding that “it was a real bonding moment for us.”
“A week later, I called him up, ran it back,” Simmons continued. “We did some more.”
In a new episode released Tuesday, Simmons said he was unaware that such bets could not be made.
“I talked about how I got my daughter’s boyfriend to place some bets for me in Massachusetts because I was in L.A. [I] did not know about the proxy rules,” he said. “Yeah, there are some real rules with this stuff, and they’ve ruled that not only are the bets going to be voided — and I learned my lesson.”
Simmons said he thought proxy betting was allowed. “There you go, lesson learned,” he said.
Simmons, a former ESPN columnist and commentator, is one of the most popular podcasters in the country. “The Bill Simmons Podcast,” as of Tuesday, ranked No. 22 overall and No. 2 in the sports category on Spotify.
Spotify acquired The Ringer — a sports and pop culture website and podcast network — in 2020 for more than $200 million, according to reports.
This post appeared first on https://www.nbcnews.com
The Athletic found its former NFL reporter Dianna Russini had a close, “awkward” and “uncomfortable” relationship with coach Mike Vrabel that she should’ve disclosed, the New York Times-owned digital sports publication said Thursday.
However, Mike Semel, The Athletic’s editorial director for standards and quality, who led the probe into Russini’s work, said he did not uncover “clear” evidence that the publication’s one-time NFL insider wrongly propped up Vrabel’s professional interests.
Russini resigned from The Athletic in April, less than a week after photos of she and the married Vrabel, 51, at an Arizona hotel drew scrutiny.
“I’ve not found a clear link to conclude that Russini used her platform to help promote Vrabel or help his teams during her time at The Athletic,” Semel wrote in a piece published Thursday.
“That said, there are examples of Russini writing glowingly of Vrabel that in hindsight are awkward or even uncomfortable.”
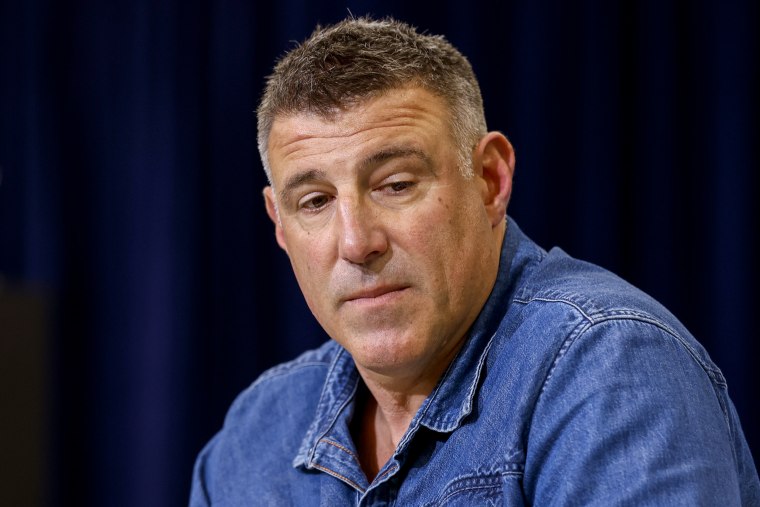
Mike Vrabel of the New England Patriots on Feb. 25 in Indianapolis.Lauren Leigh Bacho / Getty Images file
Semel said he “reviewed 903 stories and 77 videos published on The Athletic site and app that carried Russini’s byline, co-byline, a contributor line or a mention of her reporting” in addition to “204 episodes of the Scoop City podcast, produced by The Athletic and co-hosted by Russini.”
Semel also looked over “25 off-platform appearances or interviews for which she was in some way representing The Athletic and interviewed 14 Athletic staffers.
Semel’s piece did not mention any interviews with Russini herself for this probe.
Russini, 43, could not be immediately reached for comment on Thursday.
“Russini’s relationship with Vrabel was in clear violation of The Athletic’s standards,” according to Semel. “Regardless of whether the relationship was romantic, it was a breach and should have been disclosed.”
In addition to several gushing comments Russini has made about Vrabel on various platforms, Semel zeroed in on a 2023 “What I’m Hearing” column, in which she wrote that Vrabel, then head coach of the Tennessee Titans, wouldn’t be fired.
“Angry Tennessee Titans fans can stop hoping owner Amy Adams Strunk fires Vrabel. It’s not happening. Based on multiple conversations with high-ranking Titans officials, the franchise strongly and collectively believes it has the right coach for long-term success,” according to Russini.
The Titans fired Vrabel two months later.
Vrabel returned to coaching in 2025 and led New England to one of the greatest turnarounds in recent NFL history. The 2025 coach of the year, Vrabel took a squad, which had gone 4-13 in consecutive campaigns, to a 14-3 mark and AFC title this past season.
This post appeared first on https://www.nbcnews.com
Oil giant Chevron confirmed that it will expand operations in Venezuela after President Donald Trump announced an ambitious deal to develop the nation’s oil reserves and give the Pentagon a stake in the profits.
Chevron, the only U.S. oil company with a major presence in Venezuela, said Wednesday that it has been assigned additional acreage in the Orinoco Belt, where it has active operations. The company plans to invest more than $7 billion over the next five years, with the goal of more than doubling its current production to about 600,000 barrels a day.
“Chevron’s history in Venezuela spans more than a century, and our expanded position reflects our confidence in the country’s deep resource potential,” CEO Mike Wirth said in a prepared statement.
Venezuela holds the world’s largest proven reserves, totaling more than 303 billion barrels of crude oil, according to OPEC’s 2025 Annual Statistical Bulletin. Saudi Arabia is a distant second with 267 billion barrels.
Yet because Venezuela’s energy infrastructure is severely degraded and the nation is operating under international sanctions, its daily production is just over 1 million barrels, compared with the 10 million to 11 million barrels that Saudi Arabia produces each day. The U.S. produces almost 14 million barrels per day.
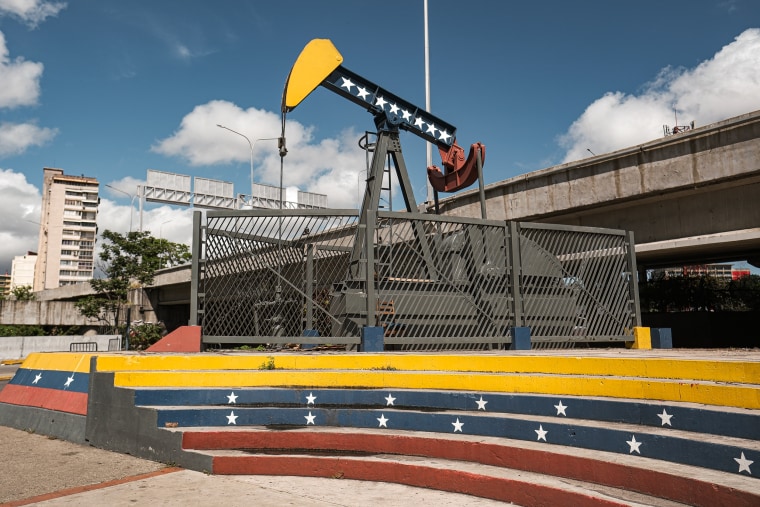
Venezuela holds the world’s largest proven reserves, totaling more than 303 billion barrels of crude oil, according to OPEC’s 2025 Annual Statistical Bulletin.Diko Betancourt / Anadolu via Getty Images
Chevron, the second-largest U.S. oil company, has had a presence in Venezuela since 1923.
U.S. Energy Secretary Chris Wright on Wednesday attended a ceremony in Venezuela’s capital in which Chevron, Italian oil company Eni and other energy companies signed agreements with the South American country’s government.
“President Trump’s mission in Venezuela is straightforward. The mission is to bring peace, freedom, opportunity and prosperity to the people of Venezuela,” Wright said in Caracas. “I believe the deals that are signed today — tens of billions of dollars of investment, ultimately many thousands of jobs — are critical in starting this ball rolling of peace, opportunity and prosperity for everyone in Venezuela.”
The White House confirmed Monday that it is partnering with North American Blue Energy Partners, NABEP, as part of Trump’s push to tap into Venezuela’s oil industry.
Yet the agreement has been met with skepticism from energy experts who say it will take years to revive Venezuela’s oil industry, which is in disarray after years of neglect.
There are also questions about whether Venezuela’s acting president, Delcy Rodríguez, has the authority to give NABEP 100-year rights over 17 oil fields with reserves of 65 billion barrels — and whether future Venezuelan or American administrations would overturn the agreement.
An oil tanker is anchored in Lake Maracaibo in Cabimas, Venezuela, on Monday. Ariana Cubillos / AP
Venezuela’s constitution states that arrangements like the one that the United States has entered must be approved by the National Assembly, which has not happened, wrote Ian Vásquez, vice president for international studies at the Cato Institute.
“The deal lacks legitimacy since it was agreed to with a dictatorship that has clung to power for decades through violence and by committing what was probably the largest electoral fraud in Latin American history in 2024,” Vásquez wrote. “The agreement was also reached under overwhelming pressure, military and otherwise, from the United States. As such, any future Venezuelan democracy will question the deal, thus undermining confidence in the current arrangement.”
The ruling party-controlled National Assembly expressed support for the agreement during its Tuesday session, but lawmakers held no debate or voted to approve it.
Wright on Wednesday pushed back on criticism, telling reporters that the deal is “a massive win” for both countries.
“Because what it’s going to do is take resources that are underground, not helping anyone, and invest capital and money and technology and bring them to the surface to better the lives of Venezuelans, better supply energy to Americans,” Wright said during a joint press conference with Rodríguez.
Trump has eyed Venezuela’s oil since the January capture of then-President Nicolás Maduro and has pressed to get U.S. businesses back into the country. “We have Exxon going in, we have Chevron going in. We have our big oil companies going in,” he said that same month.
He suggested again on Monday that other U.S. oil majors were preparing for a return, though other than Chevron, there is no evidence of that.
Exxon Mobil CEO Darren Woods said in January that Venezuela was “uninvestable.” An Exxon spokesman said this week that “nothing has changed.”
Venezuela nationalized its oil industry in 1976 and created the state-owned company Petróleos de Venezuela S.A. A second nationalization occurred in 2007, when President Hugo Chávez pushed foreign oil companies into state-controlled joint ventures. Ronaldo Schemidt / AFP via Getty Images
The history of U.S. oil majors in Venezuela explains the hesitation.
Venezuela nationalized its oil industry in 1976 and created the state-owned company Petróleos de Venezuela S.A. A second nationalization occurred in 2007, when President Hugo Chávez pushed foreign oil companies into state-controlled joint ventures and seized the assets of companies that refused. Chevron agreed to a joint venture. Others, including Exxon and ConocoPhillips, refused, and Venezuela took their assets.
Trump has said that the agreement with Venezuela would “substantially lower” gasoline prices in the U.S. However, analysts have repeatedly warned that Venezuela’s dilapidated oil infrastructure will require years of restoration work and tens of billions of dollars to resuscitate.
“It could take 2 to 4 years to get new greenfield facilities online in the Orinoco region,” Amy Jaffe, director of the Global Energy, Climate, and Sustainability Lab at New York University, said in an email. “Other places where there is no pipeline and other kinds of support infrastructure could take longer.”
Meanwhile, the national average price for a gallon of regular gasoline jumped overnight to $4.12, according to the motor club AAA. That is 93 cents more than it cost at this point last year.
This post appeared first on https://www.nbcnews.com
President Donald Trump on Monday called for bipartisan tax incentives to help a domestic TV and movie industry that has seen large chunks of its business move overseas in recent years.
Trump wrote on Truth Social that meetings were “being set up with the Leaders of both Parties in order to get this done.”
“It should be Bipartisan, especially since so much money is being lost in California, and other largely Blue States,” he wrote. “I am going to suggest that Republicans and Democrats get together, and immediately craft Legislation to save the Movie, Television, and Entertainment Business in America.”
Trump indicated that his call to help Hollywood — an industry that Republicans often rail against and one that resides in solidly blue California — was influenced in part by actor Jon Voight, who was a 2024 campaign surrogate for him.
Voight, whom Trump has called his “Hollywood ambassador,” has helped shape Trump’s policy toward the entertainment industry during his second term. In May 2025, Trump met with Voight before he proposed tariffs on films produced overseas.
Voight did not immediately respond to a request for comment Monday night.
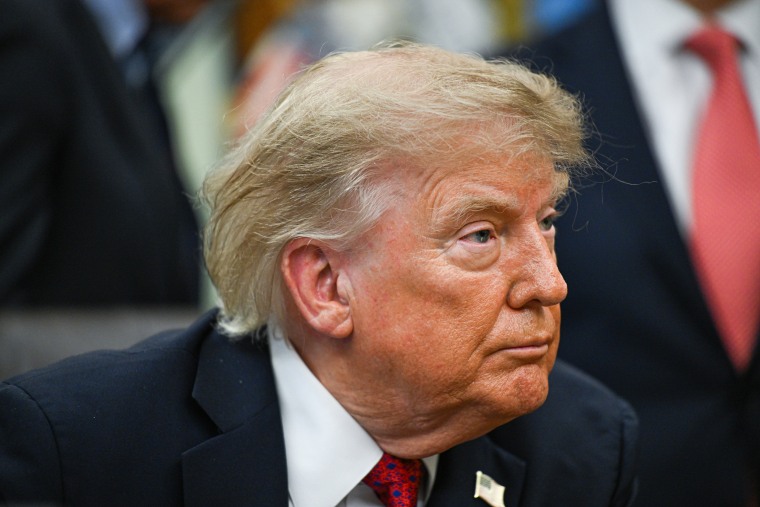
President Donald Trump in the Oval Office of the White House on Monday.Annabelle Gordon / Bloomberg via Getty Images
Trump’s Truth Social post drew immediate support from Democrats who are usually critical of him and his administration’s policies.
Sen. Adam Schiff, D-Calif., a frequent Trump target, said he was in “strong agreement” with Trump on this one.
“Congress should immediately take up and pass a federal film tax incentive to bring back these good-paying jobs that we’ve lost to other countries,” Schiff wrote on X. “Let’s work together — Republicans and Democrats — to get this done, and bring the movie magic back to America.”
Rep. Laura Friedman, D-Calif., praised the proposed measure and called for swift passage.
“For more than a year I’ve been sitting down with Jon Voight, Congressional colleagues, the unions, studios, and producers to build the case for a national film and television tax credit,” Friedman said in a statement. “There’s no reason Canada, the UK, or Australia should be taking our jobs. We still have the best crews on the planet. It’s time we made it possible for them to stay where they belong: in America.”
Friedman said last September that the proposed tariffs on foreign films were recognition from Trump that the U.S. was losing its domestic film and TV industry but that the path forward was a tax credit, not tariffs.
Trump’s announcement Monday was also embraced by the industry itself.
Charles Rivkin, the CEO of the Motion Picture Association, the trade group representing major film studios in the U.S., said in a statement that the group applauded Trump’s support for tax incentives.
“For over a century, American studios, casts, and crews have produced the films and series that the world wants to see. A federal incentive would be a landmark step toward bringing more production to local communities in all 50 states, strengthening our nation’s economy, and making our country a more competitive place to produce, create, and tell great stories,” Rivkin said in his statement.
While Trump did not lay out any financial details in his post, he predicted that the money spent on the tax incentives “will be made up tenfold by the money pouring into the Treasury’s coffers.”
This post appeared first on https://www.nbcnews.com
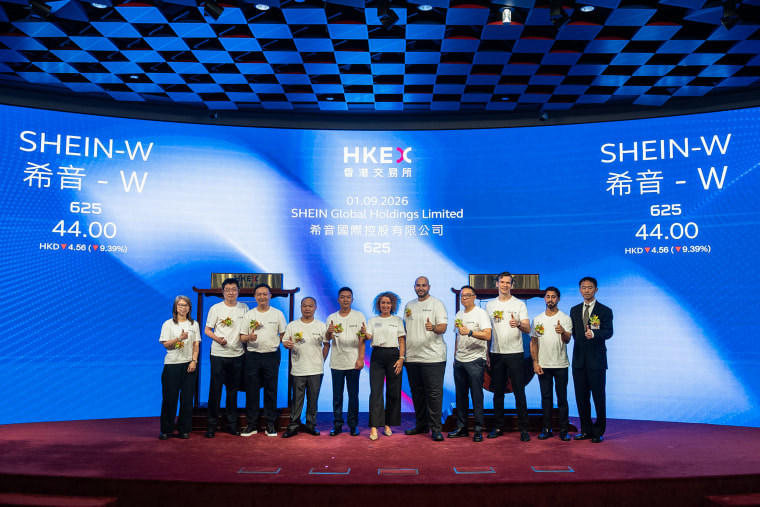
HONG KONG — Shares in online fast-fashion retailer Shein fell 8% in their first day of Hong Kong trade on Tuesday, with investors worried about the impact of setbacks that long delayed its listing and have undermined its competitive advantages.
Known globally for selling $5 tops and $10 dresses, Shein has been humbled by tariff and duty changes in the U.S. and Europe. Intense scrutiny of its business practices in the West also hampered its attempts to list in New York and London, which were ultimately blocked by Chinese authorities.
The stock was trading at around 44.6 Hong Kong dollars ($5.68) in morning trade, valuing the company at around $24 billion ($3 billion), far below its 2022 peak of nearly $100 billion ($12.8 billion). Hong Kong’s Hang Seng Index was down 0.6%.
“As a new company listed in Hong Kong, we will continue to innovate, optimize and cooperate with our supply chain partners for mutual benefit and win-win results,” Shein Chief Financial Officer Leigh Gui said at the opening gong ceremony.
Shein CEO Sky Xu, second left, with other guests at the company’s listing ceremony in Hong Kong on Tuesday. Chan Long Hei / AP
Founder and CEO Sky Xu, known for disliking the limelight, did not speak at the event though later took pictures with Shein employees onstage. He declined to respond to Reuters’ questions.
“I think the weak debut shows that even after the huge valuation reset, investors still don’t see Shein as obviously cheap,” said Charu Chanana, chief investment strategist at Saxo.
Chanana said Shein was valued at 15 times forward earnings, more than double the multiple for PDD, the owner of rival Temu, which meant “investors were being asked to pay a premium despite weaker growth visibility and significant regulatory and trade risks.”
Demand for Shein’s stock during the IPO was tepid compared with high-profile offerings from the AI and robotics sectors.
The retail tranche was subscribed 5.63 times, while the international portion was subscribed 2.59 times. Some deals have been hundreds of times oversubscribed, especially from Hong Kong’s army of retail investors who track IPOs very closely.
The amount sold in the IPO represents about 6.6% of Shein’s enlarged share capital. Cornerstone investors took about one-fifth of the IPO and are locked up for six months, leaving roughly 5% freely tradable.
Last year, the U.S. ended the de minimis duty exemption for e-commerce shipments under $800 that had powered Shein’s direct-shipping model. The European Union recently followed suit, imposing fees on low-value packages.
Shein’s net income slid 39% last year, and it swung to a loss in the first quarter.
Shein has said it expects first-half operating profit margin to be slightly lower than in the first quarter, hurt by higher customs duties, tariffs, fees and logistics costs in Europe and the Middle East.
“New markets could help offset slower growth in the U.S. and Europe, but lower spending power in developing markets may limit the benefit if delivery costs stay high,” said Lorraine Tan, director of equity research at Morningstar.
Shein has been trying to widen beyond its own-label ultra-cheap fast fashion, having expanded its third-party marketplace and bought U.S. apparel brand Everlane in May.
In its prospectus, it said it aims to offer marketplace and supply chain services to more brands, in the footsteps of French brand Pimkie and British brand Missguided, which it bought in 2023.
The IPO has helped Shein compensate early investors who invested at much higher valuations. The company has agreed to make cash payments totaling about $3.5 billion and share adjustments to some preferred shareholders.
“This IPO is not just a fundraising event — it is also, and probably more of, a capital-structure event,” said Jianggan Li, CEO of consultancy Momentum Works.
This post appeared first on https://www.nbcnews.com